Ownership
Annual inspections and prepurchase evaluations
What an annual inspection records, how to define a prebuy, and how to assess records, repair estimates, and first-year maintenance.
FlyHdg360 · · 6 min read
Read the inspection entry
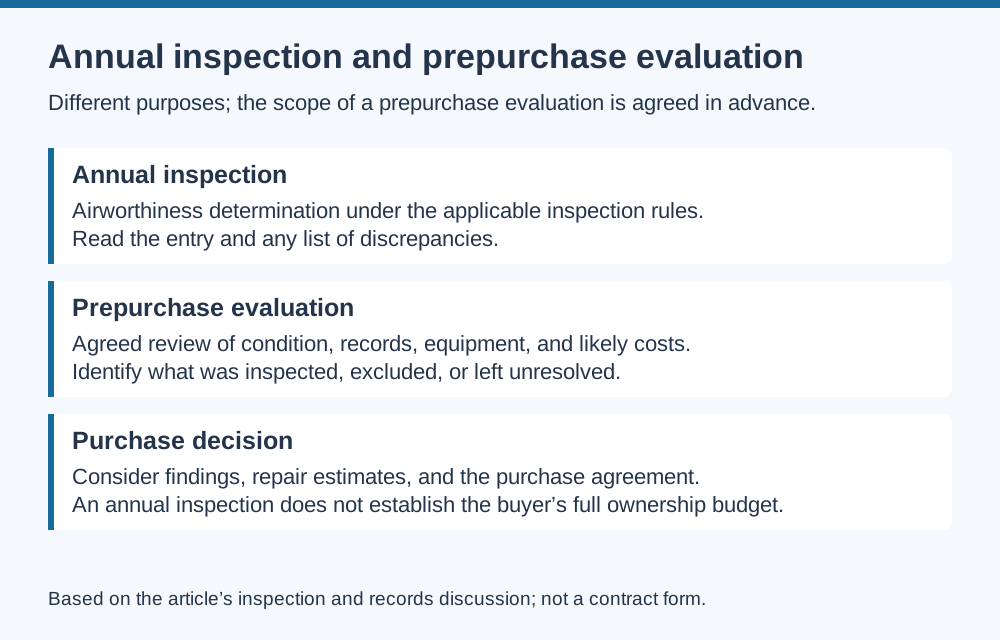
A listing’s reference to a recent annual should be checked against the actual maintenance records. Under 14 CFR 43.11, an inspection entry includes the inspection type and extent, date, aircraft total time, and the identifying information of the person approving or disapproving return to service. The regulation provides for both outcomes.
The date alone therefore does not establish that the aircraft was approved for return to service. Review the entry and any associated discrepancy documentation with the evaluator. Identify subsequent work and any unresolved questions about the inspection status.
A recent inspection also does not establish current condition indefinitely. The buyer’s evaluation needs to account for the aircraft’s use, work, and condition since that inspection.
Define the prepurchase evaluation
In AOPA’s interview with maintenance specialist Paul New, he distinguishes the annual’s airworthiness focus from a prepurchase evaluation’s assessment of future ownership expense. He also emphasizes relevant experience with the aircraft type. A prebuy report is useful only in relation to the scope and expertise behind it.
Agree on the evaluation before work starts. Specify the records review, physical examination, access required, exclusions, deliverables, and process for authorizing additional investigation. Ask how findings will be documented and when the evaluator will be available to explain them.
The work should address the aircraft being considered, including its model, configuration, and known history. A generic checklist may help organize the visit, but it does not explain which model-specific issues were investigated.
Source: AOPA: Prepurchase evaluations — interview with Paul New
Collect records before the visit
Ask the evaluator which records are needed in advance. Section 91.417 identifies required aircraft-status records, including total time, life-limited parts, inspection status, and applicable airworthiness-directive status. For recurring AD actions, the records include when the next action is required. The section also specifies records retained and transferred with an aircraft at sale.
For the evaluation, request the available airframe, engine, and propeller histories, recent work orders, relevant alteration and equipment documentation, and current loading information. Let the evaluator identify additional requirements for the specific aircraft.
Maintain a document request list showing what has been received, what is missing, and who is obtaining it. If an item remains unavailable, record the effect on the evaluation. An unsupported assumption should remain an unresolved question rather than become a finding of compliance or condition.
Source: 14 CFR 91.417: Maintenance and aircraft-status records
Verify the equipment needed for the intended operation
Provide a written description of the planned use: normal load, expected utilization, typical routes, and equipment capabilities required. This gives the evaluator and any avionics specialist a defined set of purchase questions.
For installed avionics, identify exact equipment and configuration rather than relying on broad listing descriptions. Ask the appropriate specialist to verify the documentation and limitations relevant to the intended capability. The presence of a familiar display or navigator does not, by itself, establish every operational capability a buyer associates with it.
Check the aircraft-specific loading and performance information separately from equipment. A suitable panel does not resolve whether the intended passengers, baggage, and fuel fit the mission. Record any planned upgrades as buyer-selected work so they remain distinguishable from condition findings.
Classify findings and unresolved work
The report should distinguish a documented condition from a suspected problem requiring investigation and from an elective upgrade. Each category leads to a different decision and a different level of cost certainty.
For an intermittent fault, record whether it was reproduced and whether a diagnosis was established. If not, request the proposed diagnostic work and its limits. A component replacement estimate should not be treated as a confirmed repair solution when the cause remains uncertain.
For a finding that affects airworthiness or the intended operation, have the appropriately qualified person explain the effect and required action. Keep that technical determination separate from the commercial discussion about price or responsibility for payment.
A useful finding record contains the evidence, consequence, next action, person responsible, and status. Closing the item should require an identifiable result, not simply a note that it was discussed.
Review what each estimate includes
Identify whether each amount is a written quote, a preliminary estimate, a diagnostic allowance, or a buyer’s budget provision. Those categories should not be combined into one apparently firm total.
For defined work, ask whether the amount includes removal and installation, parts or repair service, labor, shipping, applicable taxes, and the checks and records associated with completing the work. Confirm any exclusions and the circumstances in which the price can change.
For a part sent out for evaluation, distinguish the cost of inspection from the possible repair or replacement cost. Record any exchange-core conditions or additional charges identified by the supplier. Use the actual quote rather than assuming all quoted component prices have the same terms.
An unknown amount should remain marked as unknown, with a request for the missing estimate. Entering zero makes the budget look more complete while understating the unresolved expense.
Prepare a first-year maintenance schedule
Convert the report into a work list with estimated cost, scheduling assumptions, and likely downtime. Separate work needed before the intended operation, scheduled future maintenance, elective improvements, and items awaiting further investigation.
Ask the relevant shops about start dates, parts availability, outside services, and expected completion. A repair estimate does not establish that the shop has a slot or that a needed component is available. Record whether dates are confirmed or provisional.
Discuss whether related jobs should share a visit, including the effect of an unavailable part on other work. Do not assume that combining tasks necessarily shortens downtime.
Compare the resulting schedule with the intended flying. This is where the report becomes an ownership plan: the buyer can see which costs and interruptions are already identified and which remain uncertain.
Resolve the purchase decision within the agreement
Review the evaluation deadline, document requests, further-investigation process, and purchase options with the professionals handling the transaction. The effect of a finding on acceptance, price, repair obligations, or cancellation depends on the actual agreement. A technical report does not itself establish those contractual rights.
Keep the report, written follow-up answers, estimates, and unresolved-item list together. Before making the purchase decision, identify which remaining uncertainties could change the decision and whether further work can resolve them.
The completed file should distinguish the aircraft’s documented status, expected ownership work, discretionary upgrades, and open questions. That provides a firmer basis for a purchase than the inspection date or a single estimated repair total.